You open your credit card statement, expecting the usual transactions. Groceries, gas, maybe a few online purchases.
Then you notice something unexpected.
Annual Membership Fee: $95.
You haven’t booked a flight in months. You barely use the card’s rewards. And now you’re wondering why you’re paying nearly $100 just to keep it.
Sound familiar?
An annual credit card fee isn’t necessarily a waste of money. Some cards offer valuable benefits that justify the cost. But plenty of people pay for perks they rarely use, simply because they never stop to review their accounts.
The good news is that you have options.
You might qualify for a fee waiver, switch to a less expensive card, or discover that keeping your current card actually makes financial sense.
This guide explains seven practical ways to evaluate your credit card’s annual fee, reduce unnecessary costs, and make a decision that fits your financial situation.
What Is an Annual Credit Card Fee?
An annual credit card fee is a recurring charge that some credit card companies collect for providing access to a particular credit card.
Unlike interest charges, an annual fee generally doesn’t depend on whether you carry a balance.
You may owe the fee even if you rarely use the card.
Some credit cards have no annual fee. Others charge annual membership fees in exchange for rewards programs, travel benefits, or other features.
For example, imagine two hypothetical credit cards:
| Feature | Card A | Card B |
|---|---|---|
| Annual fee | $0 | $95 |
| Cashback | 1.5% | 3% on eligible purchases |
| Travel benefits | Limited | Additional benefits |
| Best suited for | Simple everyday use | Eligible higher spending |
At first glance, Card B looks more attractive because it offers a higher rewards rate.
But that doesn’t automatically make it the better choice.
If you don’t spend enough in eligible categories, the extra rewards may never cover the annual fee.
The important question isn’t how many benefits your credit card advertises. It’s how much value you actually receive.
If you’re trying to reduce unnecessary expenses, AI budgeting tools can help you track spending, identify recurring charges, and build a more realistic monthly budget.
Annual Credit Card Fee vs. APR: What’s the Difference?
These two charges are easy to confuse.
An annual fee is a membership-related cost.
APR, or annual percentage rate, represents the annualized interest rate associated with borrowing on the card.
A card can have no annual fee and still charge substantial interest when you carry a balance.
Likewise, a premium rewards card may charge an annual fee even when you pay your statement balance in full.
When comparing cards, review both costs.
The Consumer Financial Protection Bureau’s credit card agreement database provides access to agreements containing pricing and fee information.
The Consumer Financial Protection Bureau’s credit card agreement database provides access to agreements containing pricing and fee information.

7 Smart Ways to Avoid an Annual Credit Card Fee
Not every strategy will work for every cardholder. Issuer policies, account history, rewards rules, and credit circumstances all matter.
Still, these seven approaches can help you avoid paying more than necessary.
1. Ask Your Credit Card Issuer for an Annual Fee Waiver
Before canceling a credit card, consider making a phone call.
Some issuers may offer retention incentives to eligible customers who are thinking about closing their accounts.
These offers can take different forms, including statement credits, bonus rewards, or other account-specific benefits.
A complete annual fee waiver is possible in some circumstances, but it isn’t guaranteed.
What should you say?
Try something simple:
“I’ve been reviewing my credit card expenses, and I’m not sure the annual fee makes sense for me anymore. Are there any retention offers or fee-waiver options available?”
You don’t need an elaborate negotiation strategy.
Explain your concern and ask what options are available.
If the representative offers a spending-based incentive, calculate whether meeting the requirement would encourage purchases you wouldn’t otherwise make.
Spending an extra $500 to receive a $50 credit isn’t a bargain if you didn’t need those purchases.
Important: Ask whether the offer changes your existing card terms or requires you to keep the account open for a specified period.
2. Downgrade Your Credit Card Instead of Closing It
Sometimes you like your credit card issuer but no longer need the premium card.
That’s where a product change may help.
A product change allows an eligible cardholder to switch from one card product to another within the issuer’s available options.
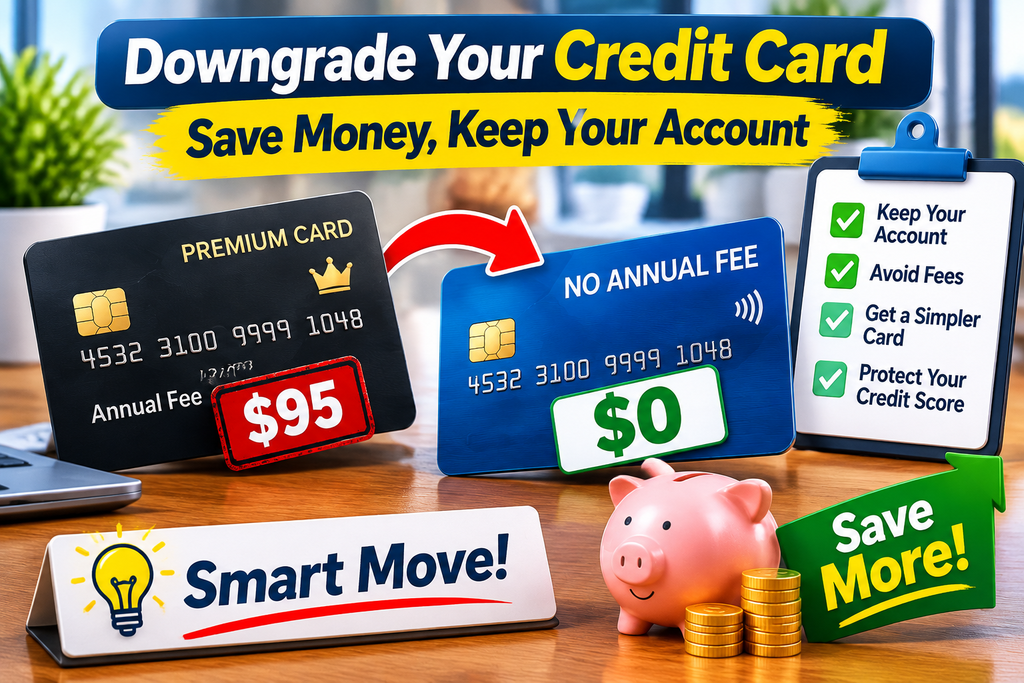
For example, you might move from a $95 annual-fee card to a no-annual-fee card.
This could reduce your future membership costs without requiring you to open a completely new account.
However, don’t assume every issuer handles product changes the same way.
Before requesting a downgrade, ask:
- Will my existing account remain open?
- Will my credit limit change?
- Will I lose unused rewards?
- Does the new card have different interest rates?
- Will a credit inquiry be required?
- Can I receive a refund of the current annual fee?
Some card products cannot be converted into certain others.
Others may have eligibility requirements.
A downgrade is worth investigating, but confirm the consequences before agreeing to the change.
3. Consider a No-Annual-Fee Credit Card
A premium card isn’t automatically better than a basic card.
If your spending is modest or you don’t use premium benefits, a no-annual-fee credit card may be sufficient.
Many consumers can find cards offering everyday rewards without an annual membership charge.
But choosing a card based only on its annual fee would be a mistake.
Imagine a no-annual-fee card that charges a higher interest rate than another card you’re considering.
If you regularly carry a balance, the additional interest could outweigh any savings from avoiding the annual fee.
Look at the complete cost.
That includes purchase APR, balance transfer fees, foreign transaction fees, late fees, and other relevant terms.
A $0 annual fee doesn’t mean a credit card is free to use under every circumstance.
Choosing a no-annual-fee credit card is just one way to save money. Following smart personal finance strategies can also help you manage everyday expenses, reduce unnecessary spending, and build long-term financial stability.
4. Calculate Whether Your Credit Card Rewards Cover the Annual Fee
This is where the decision becomes interesting.
A card with a $95 annual fee can be a good deal for one person and a poor deal for another.
Let’s compare two hypothetical cards.
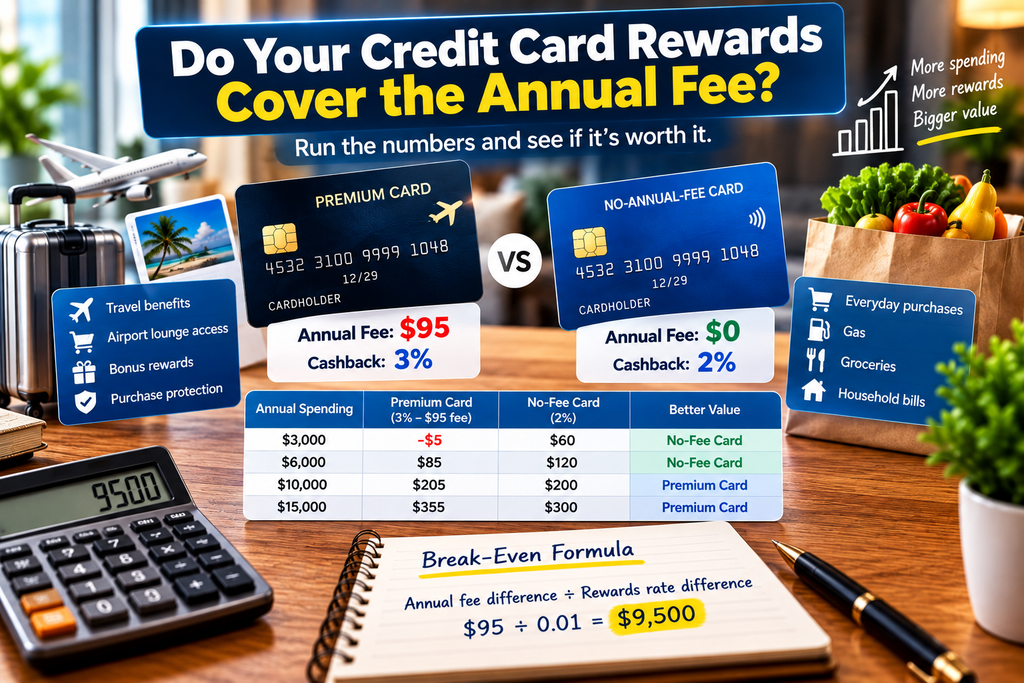
Card A: Premium Cashback Card
Annual fee: $95
Eligible cashback rate: 3%
Card B: No-Annual-Fee Cashback Card
Annual fee: $0
Eligible cashback rate: 2%
Assume both cards earn their advertised rates on every purchase in this example.
| Annual Spending | Card A Net Rewards | Card B Rewards | Better Value |
|---|---|---|---|
| $3,000 | -$5 | $60 | Card B |
| $6,000 | $85 | $120 | Card B |
| $10,000 | $205 | $200 | Card A |
| $15,000 | $355 | $300 | Card A |
Notice something important?
The premium card doesn’t become more valuable simply because it offers a higher cashback percentage.
The annual fee changes the calculation.
In this simplified example, Card A begins outperforming Card B when eligible annual spending exceeds $9,500.
That’s the break-even point.
Of course, real rewards programs often have spending caps, category restrictions, exclusions, and changing redemption values.
You should calculate the difference using your actual spending patterns.
A Simple Annual Credit Card Fee Break-Even Formula
For two cards with different rewards rates:
Break-even spending = Annual fee difference ÷ Rewards rate difference
Using the example above:
$95 ÷ 0.01 = $9,500
This calculation works when the rewards rates are consistent across the purchases being compared.
If your premium card offers travel credits or other benefits, include only the value you realistically expect to use.
Don’t count a $200 hotel credit as $200 in savings if you wouldn’t have booked that hotel otherwise.
5. Check Whether Your Annual Credit Card Fee Is Refundable
What if the annual fee has already appeared on your statement?
You may still have options.
Before requesting an annual fee refund, review your card’s terms using the CFPB credit card agreement database to understand the issuer’s fee and refund policies.
Some credit card agreements provide refunds under specific conditions.
However, the rules vary by issuer and card product.
For example, a cardholder agreement available through the CFPB for an HSBC credit card describes an annual or periodic membership fee refund when an account has not been used and is closed within 90 days of opening.
That is an example of a particular agreement—not a universal 90-day refund policy.
Another agreement in the CFPB database describes a different refund window for an annual fee after it appears on a billing statement.
The lesson?
Never assume that every credit card company follows the same refund policy.
Instead, review your cardholder agreement and contact your issuer.
Ask whether the fee can be refunded after a downgrade or account closure.
You can also use the CFPB credit card agreement database to research publicly available agreements.
6. Think Carefully Before Closing a Credit Card
Let’s say your card charges $95 annually, and the issuer won’t waive the fee or offer a suitable downgrade.
Closing the account may seem like the obvious solution.
Sometimes it is.
But there’s another factor worth considering: your credit score.
Closing a credit card can reduce your available credit.
That may increase your credit utilization ratio, which is the percentage of available revolving credit you’re using.
Here’s a hypothetical example.
Before closing the card:
| Account | Credit Limit | Balance |
|---|---|---|
| Card A | $5,000 | $1,000 |
| Card B | $5,000 | $0 |
| Total | $10,000 | $1,000 |
Your overall credit utilization is 10%.
Now imagine you close Card B.
Your available credit falls to $5,000 while your balance remains $1,000.
Your utilization rises to 20%.
That change could affect your credit score, although the actual impact depends on your broader credit profile.
The CFPB explains that closing a credit card can lower a credit score in some situations because it may increase utilization. It also notes that closing an account can make sense when annual fees or unfavorable terms outweigh the benefits.
That doesn’t mean you should keep paying an unnecessary annual fee forever just to protect your credit score.
It means you should consider the full picture.
If you decide to close the card, remember that any outstanding balance remains payable under your agreement.
The CFPB provides additional guidance on closing a credit card account.
7. Review Your Annual Credit Card Fee Before Renewal
One of the easiest ways to avoid unnecessary credit card expenses is to review your account before the next annual fee.
People often remember to compare streaming subscriptions, phone bills, and insurance premiums.
Credit card membership fees deserve the same attention.
Set a reminder several weeks before your expected renewal.
Then review your actual rewards, benefits, and expenses.
Ask yourself three questions:
Did this card save me more money than it cost?
Would a no-annual-fee card meet my needs?
Is there a better option available from my current issuer?
If the card no longer makes financial sense, contact your issuer before the next fee.
Under applicable U.S. credit card rules, issuers generally must provide advance renewal notices for certain cards with periodic renewal fees. Those notices include information about how and when a cardholder may terminate credit availability to avoid a renewal fee, where applicable.
However, you should still review your own agreement and statements rather than relying exclusively on reminders.
Should You Pay an Annual Credit Card Fee or Avoid It?
The answer depends on what you receive in return.
Consider these three hypothetical situations.
Situation 1: The Occasional Traveler
Sarah takes one vacation each year.
Her premium travel card costs $250 annually.
She rarely uses airport lounges and doesn’t consistently use the available travel credits.
Although the card advertises impressive benefits, Sarah estimates that she receives only $90 in annual value.
For her, the annual fee probably isn’t worthwhile.
Situation 2: The Frequent Traveler
Michael travels regularly for work.
He pays a $250 annual fee but receives travel-related benefits that he would otherwise purchase.
After calculating the benefits he actually uses, he estimates their annual value at $420.
If those benefits genuinely replace expenses he would have paid anyway, the card may provide worthwhile value.
Situation 3: The Everyday Shopper
Jessica mainly uses her credit card for groceries, gas, and household purchases.
She doesn’t travel frequently and prefers simple cashback rewards.
A no-annual-fee card offering straightforward rewards may fit her needs better than a premium travel card.
These are illustrative scenarios, not actual customer experiences.
The point is simple: the right card depends on your habits, not the size of its advertised rewards package.
Annual Credit Card Fee Decision Checklist
Before making a change, work through this quick comparison.
| Question | If Yes | If No |
|---|---|---|
| Do benefits exceed the fee? | Consider keeping the card | Explore alternatives |
| Do you use premium perks regularly? | Calculate their real value | Consider downgrading |
| Is a fee waiver available? | Review the conditions | Compare other options |
| Can you downgrade? | Check rewards and account terms | Consider other cards |
| Could closing affect utilization? | Review credit consequences | Closure may be simpler |
| Is the fee refundable? | Confirm the deadline | Plan before renewal |
This checklist won’t replace a careful review of your agreement, but it can help organize your decision.
Common Annual Credit Card Fee Mistakes
Even financially careful consumers can overlook the true cost of a credit card.
One common mistake is counting advertised rewards as guaranteed savings.
A travel credit isn’t valuable if you have to spend money unnecessarily to use it.
Another mistake is focusing on cashback while ignoring interest.
Earning $150 in rewards doesn’t help much if you’re paying substantially more in interest charges.
A third mistake is closing an account without reviewing unused rewards, recurring payments, or outstanding balances.
And finally, some consumers accept retention offers without reading the conditions.
A bonus that requires unnecessary spending may cost more than it saves.
The goal isn’t to collect the most credit card benefits. It’s to keep more of your own money.
Unexpected credit card charges aren’t the only financial risk to watch for. Scammers also send fake payment notifications, so learning how to spot a fake bank alert can help you protect your money and personal information.
Frequently Asked Questions About Annual Credit Card Fees
Can I avoid an annual credit card fee?
Yes, depending on your circumstances. You may be able to request a waiver, downgrade to an eligible no-annual-fee card, or choose a different credit card.
Can I negotiate my credit card annual fee?
You can contact your issuer and ask about retention offers or fee waivers. Approval depends on the issuer’s policies and your account.
Is an annual credit card fee charged every year?
An annual fee is generally charged according to the card’s disclosed billing terms. Review your agreement to confirm when it applies.
Can I get an annual credit card fee refunded?
Some issuers offer refunds under specific conditions. Refund eligibility and deadlines depend on your cardholder agreement and issuer policies.
Does downgrading a credit card hurt your credit score?
Not necessarily. Some product changes may preserve the existing account without a new credit application, but procedures vary. Confirm how your issuer will handle the change.
Is a credit card with no annual fee always better?
No. A card with an annual fee may offer enough useful rewards or benefits to justify the cost. Compare total costs and realistic benefits rather than the fee alone.
Should I cancel a card I never use?
Consider the annual fee, available downgrade options, potential credit-score impact, and your ability to manage the account. Keeping an unused card isn’t always necessary, especially when its costs outweigh its benefits.
Final Thoughts: Make Your Credit Card Work for You
An annual credit card fee isn’t automatically a bad expense.
Sometimes the rewards and benefits are worth paying for.
Other times, you’re spending money on features you barely notice.
The difference comes down to understanding your card, calculating its real value, and reviewing your options before renewal.
Start by checking your most recent statements.
Calculate the benefits you’ve actually used.
Then decide whether to request a waiver, downgrade your card, or explore an alternative.
And remember: saving money isn’t about avoiding every fee at any cost.
It’s about paying only for financial products that genuinely improve your situation.