What You’ll Learn
Millions of Americans depend on Social Security every month. Therefore, even a small increase can make a real difference.
The Next Year Social Security Adjustment is already becoming one of the biggest retirement topics in the United States. Many retirees want to know whether their monthly payment will increase, how inflation affects benefits, and what they should do before the new adjustment takes effect.
Early estimates suggest the 2027 Cost-of-Living Adjustment (COLA) could be around 3.8%, although the official figure will not be confirmed until the Social Security Administration announces it in October after reviewing inflation data.
In this guide, you’ll discover:
- What the Next Year Social Security Adjustment means
- Why millions of retirees are watching it closely
- Who could receive higher monthly payments
- How the adjustment is calculated
- Common mistakes to avoid
- Smart ways to prepare for the coming changes
Let’s begin.
What Is the Next Year Social Security Adjustment?
The Next Year Social Security Adjustment is the yearly increase made to Social Security benefits to help retirees keep up with inflation.
According to the U.S. Social Security Administration https://www.ssa.gov/?utm_source=chatgpt.com , annual COLA adjustments help protect benefits from inflation.
Every year, prices change. Groceries become more expensive. Rent increases. Medical costs rise. Utility bills often go up.
Without an annual adjustment, retirees would slowly lose purchasing power.
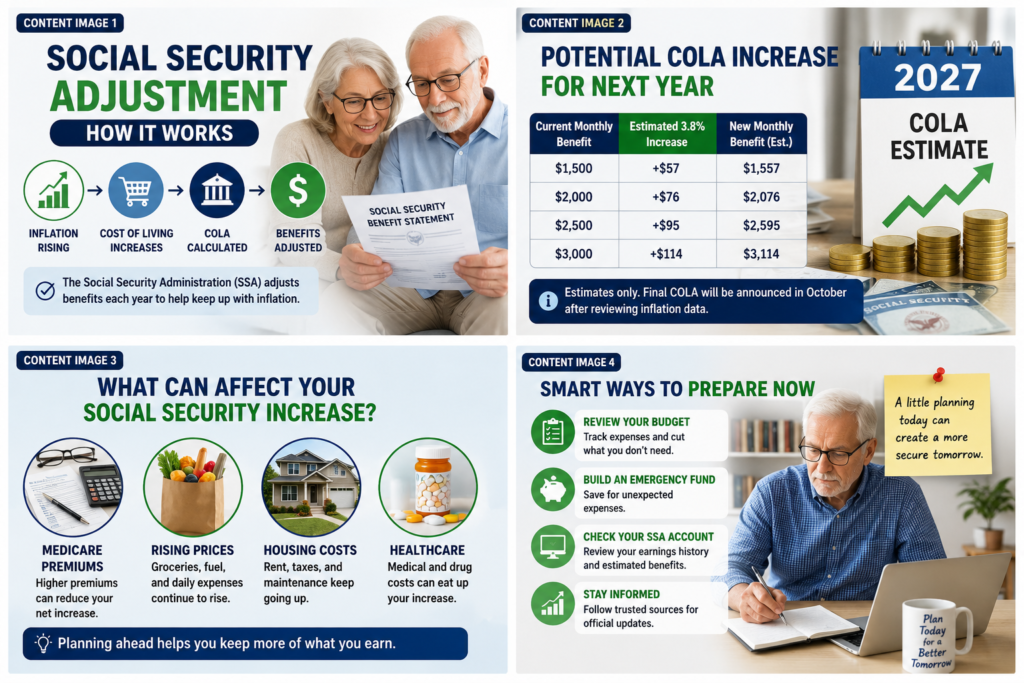
Therefore, the Social Security Administration uses the Cost-of-Living Adjustment (COLA) to help benefits better match rising living costs. The current official COLA for 2026 is 2.8%, while early forecasts for 2027 are higher but remain estimates until the official announcement.
Why Is Everyone Talking About It?
This year’s discussion is different.
Recent analysis from https://www.investopedia.com/ explains why experts are closely watching inflation and future COLA estimates.
Inflation remains one of the biggest concerns for older Americans. Food, healthcare, insurance, and housing continue to put pressure on retirement budgets.
Because of that, experts believe the Next Year Social Security Adjustment could be larger than last year’s increase if inflation trends continue through the measurement period. Current forecasts from several retirement analysts point to an estimate of about 3.8%, but the final number depends on upcoming inflation data.
That is why millions of Americans are paying close attention.
Why This Adjustment Matters More Than Ever
Many retirees live on a fixed monthly income.
When prices increase but income stays the same, everyday life becomes more difficult.
For example:
- Grocery bills rise.
- Prescription drugs cost more.
- Electricity becomes more expensive.
- Rent increases.
- Healthcare expenses grow.
Moreover, many retirees cannot easily return to work to earn extra income.
Therefore, every annual adjustment becomes extremely important.
Even a modest monthly increase can help families cover basic living expenses more comfortably.
Who Could Benefit From the Next Year Social Security Adjustment?
The adjustment may affect millions of Americans who receive Social Security benefits, including:
- Retired workers
- Disabled workers
- Survivor beneficiaries
- Supplemental Security Income (SSI) recipients who receive annual inflation-related adjustments
However, the exact increase each person receives depends on their current benefit amount.
How Is the Adjustment Calculated?
Many people think Congress simply decides the increase.
That is not how the system works.
Instead, the Social Security Administration follows a formula based on inflation.
The adjustment is calculated using the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Inflation data collected during the third quarter (July, August, and September) plays a key role in determining the annual COLA.
Because of this process, the official percentage is usually announced in October.
Why Early Estimates Can Change
You may have already seen headlines claiming a specific increase.
Remember that these are only projections.
Although several organizations currently estimate a 3.8% COLA, the official figure could still change depending on the remaining inflation reports before the announcement.
Therefore, it is always best to rely on official SSA announcements before making financial decisions.
Quick Takeaways
- The Next Year Social Security Adjustment helps protect benefits from inflation.
- Early forecasts currently suggest a possible 3.8% COLA, but it is not final.
- The official announcement is expected in October after all required inflation data is available.
- Understanding how the adjustment works can help retirees plan their finances with more confidence.
How Much Could the Next Year Social Security Adjustment Increase Your Benefits?
Could Your Monthly Payment Increase?
This is the question almost every retiree is asking.
While the official number has not been announced yet, current projections suggest the Next Year Social Security Adjustment could be around 3.6% to 3.8%, depending on inflation during the remaining months used in the COLA calculation.
However, remember one important fact.
These are still estimates.
The Social Security Administration (SSA) will announce the official adjustment after it reviews third-quarter inflation data.
Therefore, avoid making financial decisions based only on early predictions.
Why a Small Percentage Can Make a Big Difference
At first glance, a 3% or 4% increase may not sound exciting.
However, over an entire year, that increase can provide hundreds of extra dollars.
For retirees living on a fixed income, every dollar matters.
Moreover, higher monthly benefits can help cover rising costs for:
- Groceries
- Prescription medications
- Housing
- Utilities
- Transportation
- Healthcare
Even a modest increase may reduce financial stress for many households.
Example of a Possible Benefit Increase
The exact amount depends on your current monthly benefit.
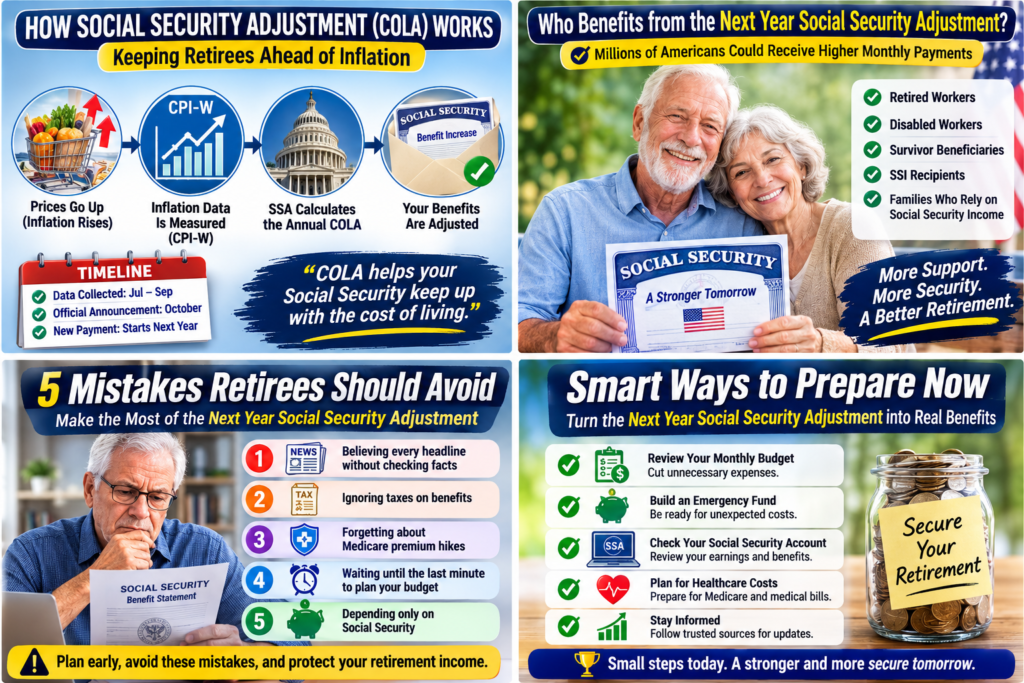
Here is a simple example using an estimated 3.8% adjustment.
| Current Monthly Benefit | Estimated Monthly Increase | New Monthly Benefit |
|---|---|---|
| $1,500 | +$57 | $1,557 |
| $2,000 | +$76 | $2,076 |
| $2,500 | +$95 | $2,595 |
| $3,000 | +$114 | $3,114 |
These examples are for illustration only.
The final increase depends on the official COLA announced by the SSA.
What Could Reduce the Real Value of Your Increase?
Receiving a higher Social Security payment does not always mean you will have more money available to spend.
Several factors may reduce the benefit of the increase.
Higher Medicare Costs
Many retirees have Medicare premiums deducted directly from their Social Security payments.
Therefore, if Medicare premiums increase, part of your COLA could disappear. Current projections suggest Medicare Part B premiums may also rise next year.
Rising Food Prices
Food inflation continues to affect household budgets.
Moreover, grocery costs often rise faster than expected during periods of higher inflation.
Housing Expenses
Rent, property taxes, and home maintenance costs have increased in many parts of the country.
As a result, some retirees may still feel financial pressure even after receiving a higher monthly payment.
Healthcare Costs
Healthcare remains one of the largest expenses during retirement.
Prescription drugs, doctor visits, and insurance costs can easily absorb part of any COLA increase.
Five Mistakes That Can Cost Retirees Money
Many people focus only on the Next Year Social Security Adjustment.
However, retirement income depends on much more than COLA.
Avoid these common mistakes.
1. Believing Every Headline
Many websites publish estimates months before the official announcement.
Some headlines make the increase sound guaranteed.
Instead, always verify important information through the Social Security Administration.
2. Forgetting About Taxes
Some retirees may pay federal income tax on part of their Social Security benefits depending on their total income.
Therefore, planning ahead is important.
3. Ignoring Medicare Premiums
A higher benefit does not automatically mean higher spending power.
Always calculate your expected Medicare costs.
4. Waiting Until the Last Minute
Many retirees review their finances only after the new payment begins.
Instead, create a budget before the adjustment takes effect.
That gives you more control over your retirement income.
5. Depending Only on Social Security
Social Security provides valuable income.
Diversifying your retirement income is important. Learning about 7 Powerful AI Investing Tools 2026 Every Investor Needs may help you make smarter long-term investment decisions.
However, many financial experts recommend combining it with savings, retirement accounts, or other income sources whenever possible.
This can improve long-term financial security, especially if inflation remains elevated.
Smart Ways to Prepare Right Now
You do not need to wait for the official announcement.
Moreover, using Best AI Finance Apps for Smarter Money in 2026 can help retirees track spending, manage bills, and create better monthly budgets.
You can start preparing today.
Review Your Monthly Budget
Look at where your money goes each month.
Identify unnecessary expenses.
If you want to simplify budgeting, these The Best AI Budgeting Apps 2026 That Actually Work can automatically track expenses and identify saving opportunities.
Small savings add up over time.
Build an Emergency Fund
Unexpected expenses happen.
A dedicated emergency fund can reduce financial stress.
Review Your Social Security Statement
Check your earnings history and estimated benefits through your official SSA account.
Correcting errors early can prevent future problems.
Delay Claiming If It Fits Your Situation
For some people, delaying benefits beyond full retirement age can result in larger monthly payments.
However, this decision depends on health, income needs, and personal circumstances, so it should be considered carefully.
Key Takeaways
The Next Year Social Security Adjustment could provide welcome relief for millions of Americans.
However, your overall retirement income depends on much more than the annual COLA.
Planning ahead, avoiding common mistakes, and understanding how inflation affects your finances can help you make the most of every dollar.
How to Prepare for the Next Year Social Security Adjustment
Don’t Wait for the Official Announcement
Many people think they should wait until the Social Security Administration announces the final adjustment.
However, waiting may not be the best strategy.
The smartest retirees prepare early. They review their budget, reduce unnecessary expenses, and understand how the Next Year Social Security Adjustment could affect their monthly income.
Even if the final increase changes slightly, planning ahead gives you more financial confidence.
Create a Retirement Budget That Can Handle Inflation
Inflation affects almost every household.
Therefore, creating a realistic monthly budget is one of the best ways to protect your retirement income.
Start by listing your essential expenses:
- Housing
- Food
- Utilities
- Healthcare
- Insurance
- Transportation
Next, compare those costs with your monthly Social Security benefit.
If your expenses are rising faster than your income, look for areas where you can reduce spending without affecting your quality of life.
Moreover, reviewing your budget every few months helps you stay on track as prices change.
Build an Emergency Fund
Unexpected expenses can happen at any time.
A medical bill, home repair, or car problem can quickly put pressure on your finances.
Therefore, keeping an emergency fund is just as important during retirement as it is while working.
Even saving a small amount each month can make a big difference over time.
If you need help getting started, read our guide on How to Build an Emergency Fund for practical saving strategies.
Review Your Social Security Account Regularly
Many people never check their Social Security records.
However, mistakes in your earnings history could affect your future benefits.
Create or log in to your official Social Security account and review:
- Your earnings history
- Estimated retirement benefits
- Disability benefits
- Survivor benefits
If you notice an error, report it as soon as possible.
Correcting problems early is much easier than fixing them years later.
Stay Informed Through Trusted Sources
Social media posts and viral headlines often spread incomplete or incorrect information.
Therefore, always verify updates before making financial decisions.
The best sources include:
- Social Security Administration (SSA)
- Medicare.gov
- AARP
- Consumer Financial Protection Bureau (CFPB)
These organizations provide accurate and regularly updated information about benefits, retirement planning, and government programs.
Frequently Asked Questions
When will the Next Year Social Security Adjustment be announced?
The official adjustment is typically announced in October after the Social Security Administration reviews third-quarter inflation data.
Will everyone receive the same increase?
Yes, the annual COLA percentage is applied across eligible Social Security benefits. However, the dollar amount each person receives depends on their current monthly benefit.
Can Medicare reduce my increase?
Yes.
If Medicare premiums increase, they may reduce part of the extra money you receive from the annual adjustment.
Is the current COLA estimate final?
No.
Current estimates are based on available inflation data.
The official percentage will only be confirmed after the Social Security Administration completes its annual calculation.
Should I change my retirement plan now?
Not necessarily.
However, reviewing your budget, reducing unnecessary expenses, and staying informed can help you prepare for any changes.
Final Thoughts
The Next Year Social Security Adjustment is more than just an annual percentage increase.
For millions of retirees, it can influence everyday decisions, from paying bills to managing healthcare costs and protecting long-term financial security.
Besides Social Security planning, exploring the Best AI Finance Tools 2026: Save Money Automatically can help improve your overall financial health.
Although early forecasts provide a useful picture, the official adjustment will depend on the latest inflation data.
Therefore, the best approach is to stay informed, rely on trusted sources, and prepare your finances before the new payments begin.
Small financial habits—such as reviewing your budget, building an emergency fund, and checking your Social Security record—can have a lasting impact.
Moreover, retirement planning is not just about reacting to yearly changes. It is about creating a financial plan that remains strong through changing economic conditions.
By understanding how the Next Year Social Security Adjustment works and taking action today, you can make more confident financial decisions for the years ahead.
Key Takeaways
- The Next Year Social Security Adjustment helps protect benefits from inflation.
- The official adjustment is announced after third-quarter inflation data is reviewed.
- Early estimates may change before the final announcement.
- Medicare costs and inflation can reduce the real value of a benefit increase.
- Planning ahead is one of the best ways to protect your retirement income.
- Always rely on official government sources for the latest updates.